Risk Radar: North America Financial Crime and Regulatory Update - October 2026
Quick Summary
Since June 1, enforcement has dominated with penalties of $1.2B+ and $350M levied against a bank and card issuer respectively for effectiveness failures, FinCEN's A7 alert tied sanctions evasion to trade-based laundering and stablecoins, and the US program-rule reform is still moving. Canada's FINTRAC is applying its tougher penalty regime, and the Wolfsberg Group and FCA both stress documented, risk-based calibration.
US
Large global bank hit with $1.2B+ in coordinated FinCEN, OCC and OFAC actions (Oct.13)
FinCEN found the bank reported over $5B insuspicious activity late, including $1B+ tied to Chinese money laundering networks and trade-based laundering at the southwest border. OFAC separately settled 475 apparent violations for $11.6M. Cited failures: alerts left uninvestigated, detection driven by outside inquiries, delayed watchlist updates and weak correspondent due diligence.
Why it matters: Supervisors are testing effectiveness, and activity matching published Treasury advisories reads as known risk. This solidly aligns with SymphonyAIs “Reengineering the Risk-Based Approach,” Always-On Compliance, and System of Intelligence strategy.
Large card issuer faces a $350M OCC penalty and a Federal Reserve order (Oct. 8)
The OCC issued a cease-and-desist order and $350M civil money penalty against a large card issuer. The Federal Reserve also issued a cease-and-desist order against the organization. The OCC cited a risk assessment built around narrow deposit products rather than the dominant card business, "systemic breakdowns" in suspicious activity monitoring, and about $13B in suspected trade-based money laundering (June 2014 to May 2025).
Why it matters: Card and charge products are squarely in scope, and risk assessments must reflect where the business actually is. This is another major enforcement actions that points directly to SymphonyAI's strategy and products for meeting these challenges and resolving these deficiencies.
FinCEN targets the Russia-linked A7 Network (Oct. 1) and Iranian charity abuse (Oct. 15)
FinCEN released an Alert that describes a wholesale sanctions-evasion service using third-country "Sub-Agent" shell companies (accounts at about 435 institutions in 83 countries), falsified trade invoices, and the ruble-backed A7A5 stablecoin, which processed at least $179.1B from February 2025 to June 2026. FinCEN also proposed a special measure (311 Action) barring funds transmittal involving Sub-Agents. SAR key term: FIN-2026-A7NETWORK. A second alert covers Iranian regime abuse of religious charity networks.
Why it matters: Shows that convergence across compliance domains (e.g. AML, Sanctions, KYC), is crucial for effectiveness, with trade-based money laundering, sanctions evasion, and digital assets squarely in scope.
AML program reform and deregulation continue (June to Oct.)
FinCEN's April proposal would replace process-based compliance with an effectiveness standard; comments closed June 9. The Federal Reserve issued a separate proposal on July 7 that departs from the OCC/FDIC/NCUA version. FinCEN also made the Corporate Transparency Act's domestic exemptions permanent (Aug. 11) and withdrew two crypto proposals (Oct.5).
Why it matters: The program rule remains proposed as we await a finalized rule, though effectiveness remains the goal.
Canada
FINTRAC applies its new penalty regime (Sept. 3) as the FATF reports on Canada (Sept. 29)
FINTRAC fined two Atlantic Canada gaming corporations C$399,712.50 and C$231,826 for failing to file suspicious transaction reports and, in one case, for a deficient risk assessment. The framework in force since March 26 allows up to $4M for individuals and $20M for entities per prescribed violation. The FATF's final evaluation of Canada urged stronger risk-based supervision and more complex money laundering prosecutions.
Why it matters: Documented, risk-based programs now carry real penalty exposure.
Global News
UK FCA sanctions review (May 28).
After assessing 150+ firms, the FCA found proactive evasion monitoring, lookbacks and tailored scenarios outperformed screening alone, and trade sanctions controls lag financial sanctions. A new FCA-OTSI information-sharing agreement means the two can no longer be treated as separate workstreams. U.S. (OFAC) and U.K. regulatory regimes are aligning in what they see as deficiencies and what they expect from institutional compliance programs.
The Wolfsberg Group.
June 23 risk-based approach guidance: "A focus on everything is a focus on nothing," so stop or redesign low-value activity and demonstrate outcomes. July 15 guidance on banking non-bank payment service providers: Tailor due diligence and expect payment transparency in line with FATF Recommendation 16.
FATF (June plenary).
The new UK Presidency (from July 1) prioritizes fraud, risk-based supervision and information sharing. Again, this shows alignment across global regulatory bodies around effective risk-based supervision and institutional compliance efforts.
U.S. Bureau of Industry and Security (June).
The 2026 Annual Economic Report chapter on stablecoins cites a disproportionate share of illicit on-chain activity and says issuer freeze tools cannot replace routine AML controls.
Related resources
Risk Radar: APAC Financial Crime and Regulatory Update - October 2026
Risk Radar: EMEA Financial Crime and Regulatory Update - October 2026
FinCrime Frontier 2026-27 Report
Reengineering the Risk-Based Approach with Agentic AI
Reengineering Sanctions Compliance: Agentic AI and the Shift to Continuous Risk and Controls
The FATF Fraud Roadmap 2026–2028: A global reset on combating fraud
FinCrime Frontier 2026-27 Findings: What's Working, What's Changing, What's Next
Learn more about Symphony Risk Intelligence
Discover the Symphony Risk Intelligence platform and begin your journey towards Always-on Compliance.
US regulators are increasingly emphasizing the effectiveness of anti-money laundering (AML) programs rather than procedural compliance alone. Recent enforcement actions highlight deficiencies in suspicious activity monitoring, risk assessments, correspondent banking due diligence, and sanctions screening. Financial institutions must demonstrate that their controls identify and address financial crime risks effectively.
FinCEN's proposed AML program reforms would place greater emphasis on risk-based compliance effectiveness rather than process-driven requirements. The proposals aim to encourage financial institutions to focus resources on material financial crime risks and demonstrate meaningful outcomes. As of October 2026, the program rule remains proposed, and institutions should monitor developments before making changes based on anticipated requirements.
FinCEN's October 2026 alert on the Russia-linked A7 Network highlights the convergence of sanctions evasion, trade-based money laundering, shell companies, and digital assets. The network allegedly used falsified trade invoices and the A7A5 stablecoin to facilitate transactions. Financial institutions should strengthen coordination between AML, sanctions screening, customer due diligence, and transaction monitoring teams.
Canada's updated FINTRAC penalty framework, effective March 2026, increases potential administrative monetary penalties for prescribed violations to C$4 million for individuals and C$20 million for entities. Recent enforcement actions emphasize the importance of suspicious transaction reporting, documented risk assessments, and effective AML controls. Financial institutions should regularly evaluate their compliance programs against applicable Canadian requirements.
Banks can demonstrate AML compliance effectiveness by connecting financial crime risk assessments to appropriate monitoring, due diligence, investigation, and reporting controls. This includes measuring detection quality, documenting decisions, reviewing emerging threats, and addressing control deficiencies. Regulatory developments and Wolfsberg Group guidance increasingly emphasize demonstrable risk mitigation outcomes rather than compliance activity volumes alone.
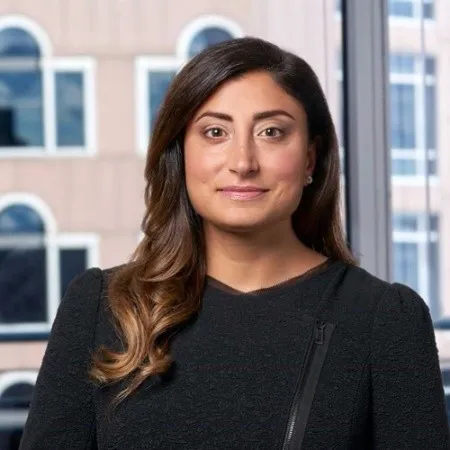
Elizabeth Callan is a recognized leader and innovator in the fightagainst money laundering and financial crime with 25 years of experience acrossintelligence, law enforcement, and the private sector. At SymphonyAI, she is atthe forefront of redefining the future of financial crime compliance and riskmanagement. She drives strategy and innovation, developing groundbreakingAI-led, intelligence-driven solutions that are transforming how globalinstitutions detect, disrupt, and prevent money laundering, sanctions evasion,and other sophisticated financial crimes. Her work is helping to shift theindustry approach from reactive, technical compliance to proactive, risk -aligned, and highly effective risk management. Prior to SymphonyAI, Elizabethserved in the U.S. intelligence and law enforcement communities. As a SeniorIntelligence Analyst at the Central Intelligence Agency and the U.S. Departmentof the Treasury, she shaped high-impact U.S. policy and enforcement actions —including Section 311 designations — while directly advising senior officialsacross the USG, including at OFAC and FinCEN, on critical threats and nationalsecurity strategies. She also served as Intelligence Liaison and Senior Advisorto the DEA’s Special Operations Division, where she led complex, large-scalemoney laundering investigations, enhanced intelligence collection efforts,trained law enforcement agents and analysts, and forged strong internationalpartnerships. In the private sector, Elizabeth has held leadership roles in financialinstitutions and consulting firms, where she built and managed investigationsteams, designed robust AML and sanctions programs, and developed riskmanagement strategies for complex products and services. A recognized subjectmatter expert, Elizabeth teaches AML and sanctions courses at the universitylevel. She holds a master's degree in economics and analytics and ACAMS’Advanced Certification in Financial Crimes Investigations (CAMS-FCI).